 Analysis by Appwee
When payday is still days away and an ordinary bill cannot wait, a small cash buffer can make a real difference. My view of Brigit: Cash Advance & Credit is that it is most useful as a short-term safety net paired with money-management tools, not as a substitute for a steady budget or emergency savings. It brings several practical ideas together, but its value depends on whether you need that mix and are comfortable linking a bank account.
A quick bridge, not a plan for recurring shortfalls
The clearest reason to consider Brigit is the possibility of getting help with a temporary cash gap. An advance can be useful when timing, rather than a lasting lack of income, is the problem: a bill is due before pay arrives, or an unexpected expense lands at an awkward point in the month. I would think of it as a bridge to the next deposit, not extra income. If the same gap appears every pay period, borrowing again can leave less room in the next one.
That distinction matters more than the convenience of requesting money. Before relying on an advance, I would check the amount needed, when the next deposit is expected, and which other bills will come due before then. If repayment would make the following week harder, the advance may simply move the pressure forward. A small buffer can solve a timing problem; it cannot fix expenses that consistently exceed income.
What the app brings together
Brigit is a finance app from developer Brigit, and its focus is broader than cash advances alone. The app combines advance access with budgeting support, credit-building options, personal loans, and ways to save money. I like that range because someone who first arrives for short-term help may also find tools aimed at building healthier habits. Still, I would assess each feature on its own rather than assuming that one good experience makes every part worthwhile.
Brigit is free to download, has an Everyone age rating, and its current version is 1086.0. It first appeared on April 16, 2018, and supports Android 8.1 or later. Its 4.8 average comes from around 337,000 ratings, with about 44,000 written reviews and over 5 million installs. Those figures suggest broad interest, but they do not tell me whether a particular person will qualify for an advance or find every tool useful.
Alerts are most useful when they change a decision
Low-balance and bill alerts can help me notice a tight week before it turns into an overdraft or a missed payment. Their practical value depends on what I do with them. If an alert arrives, I would use it as a cue to pause optional spending, check which bills are due, and decide whether moving a purchase is enough to cover the gap. That small routine makes an alert more than another notification to swipe away.
There is a trade-off: an app can point out that a balance is low, but it cannot decide which expense is safe to delay or know all the details of a household’s priorities. I would keep my own calendar or bill list as the source of truth, especially for irregular expenses. Brigit’s reminders make more sense as a second set of eyes than as a complete replacement for checking accounts and due dates myself.
More From Our Writers

OTR Makes Off-Road Roaming a Perfect Fit for Short Play Sessions

Prime Video vs. Netflix and Disney+: More Choice, More Clutter

SHAREit Review: A Fast, No-Cloud Way to Move Files

Cryptoguru Makes Crypto Trading Safer, but Can It Teach Restraint?

FC Mobile 26 Turns Soccer into a Season-Long Service

Reddit Is Worth Your Time Only If You Choose Your Communities
Credit-building takes patience and a close look at terms
The credit-building feature may appeal to someone trying to establish a record of positive payments. I would approach it with a longer horizon than the advance feature: credit progress is not something I would judge after a few days, and no app can promise a particular score change. Before enrolling in any plan, I would read what it costs, how payments are handled, and what commitment is involved, then compare that with other ways of building credit.
This is also where personal circumstances matter. If I already have a manageable way to build credit, another plan may add little. If I am new to credit, I would weigh the ongoing commitment against simpler habits such as paying existing obligations on time. Brigit’s option is worth investigating, but the label alone is not enough reason to sign up; I would want the terms to fit my budget and the goal to be clear.
Where the experience asks for trust
Getting started includes linking a bank account. That can make financial tools more relevant to a person’s situation, but it is also a meaningful privacy decision. I would take a moment to review the app’s current account-connection and privacy information before proceeding, and only link an account if I am comfortable with the arrangement. If I prefer not to connect financial accounts to an app, this setup may be a reason to choose another approach.
The app’s simple presentation is appealing, but ease of use should not replace careful reading. Before accepting an advance or signing up for a separate service, I would check the amount, timing, repayment details, and any applicable cost shown at that point. A feature can be convenient and still not be the right deal for a particular situation. I would also avoid treating a displayed option as guaranteed access; eligibility and terms can depend on the person and the product.
A realistic payday-week decision
Imagine my car needs an unplanned repair a few days before payday, while rent and a utility bill are already scheduled. I would first identify the repair amount and ask whether the mechanic can offer another payment arrangement. Then I would check the account balance and upcoming obligations, using Brigit’s alerts as a prompt rather than relying on them to make the decision. If an advance is available and repayment fits after payday, it may cover the immediate timing gap. If it would leave rent or another essential bill short, I would look for a different solution instead.
That is the kind of moment when a quick advance can be genuinely helpful: a one-off expense, a near-term deposit, and a clear repayment path. For a recurring shortfall, I would use the budgeting tools to spot patterns and consider changing the underlying plan rather than repeatedly covering the same gap. The useful insight is to treat the app’s short-term and longer-term tools differently: one may address a deadline, while the other may help me notice a habit that needs attention.
How it compares with familiar alternatives
Compared with a basic budgeting app, Brigit offers a more direct route to short-term cash alongside alerts and other financial options. A budgeting-only tool may be preferable if I simply want to track spending and would rather not connect that task to borrowing. Compared with asking a bank about an overdraft option or using a credit card, an advance app is another path, not automatically the cheapest or best one. I would compare the terms and timing of the choices available to me instead of choosing based on speed alone.
For someone who already has an emergency fund, moving money from savings may be simpler than taking an advance, provided doing so does not compromise another goal. For someone who needs a larger or longer-term loan, a personal-loan option may be more relevant, but it deserves its own careful comparison of costs and repayment obligations. Brigit’s range is convenient to explore in one place; that convenience does not remove the need to compare the specific product with alternatives.
Who is likely to get the most from it?
I would point Brigit toward people with reasonably predictable income who occasionally face a mismatch between bills and payday, and who want reminders or credit-building options in the same finance app. It may also suit someone who benefits from a nudge to check a low balance before spending. The best fit is someone who will use an advance selectively, review the terms, and treat alerts as prompts to make their own decisions.
I would skip it if I needed dependable long-term income support, did not want to link a bank account, or knew that repayment would make the next pay period unworkable. I would also hesitate if I wanted only a straightforward spending tracker and had no use for advances or credit-related services. In those cases, a simpler budgeting tool, savings plan, or direct conversation with a bill provider may better match the need.
My experience and final take
First things first, let’s talk about the setup process. Downloading Brigit was a breeze. Available on both Android and iOS, I found it on the app store and had it up and running within minutes. The interface is pretty user-friendly, which is a big plus in my book. I don’t know about you, but I’m not a fan of overly complicated apps.
Once you open the app, you’ll need to link it to your bank account. Now, I know what you’re thinking—sharing financial info can be a bit nerve-wracking. But Brigit assures users about their top-notch security measures, using bank-level encryption to keep your data safe. So, after a little hesitation, I went ahead and linked my account.
Features That Stand Out
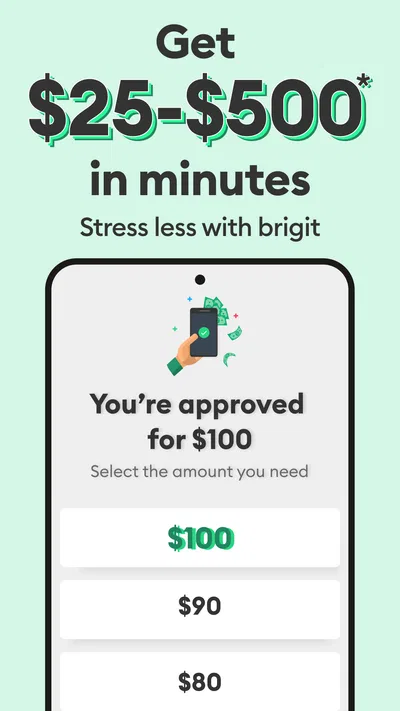
Now, onto the fun part—what does Brigit actually offer? The main feature is its cash advance service. If you’re short on cash before payday, Brigit can spot you up to $250. No questions asked, no interest charged. Just a simple fee, which I found pretty reasonable considering the convenience.
Another feature worth mentioning is the budgeting tool. Brigit helps you stay on top of your finances with real-time alerts about upcoming bills and low balance alerts. It’s like having a buddy who reminds you not to go on that online shopping spree.
Oh, and did I mention the credit builder? If you’re looking to improve your credit score, Brigit has a feature where you can subscribe to a plan that helps you build credit over time by reporting positive payments to credit bureaus.
Real-Life Experience
So, how does all this work in real life? I gave the cash advance feature a shot when I had an unexpected car repair. The request process was straightforward, and the money landed in my account the next business day. It was a lifesaver, honestly.
I also appreciated the budgeting alerts. They’re like a wake-up call when I’m about to overspend. It’s easy to ignore potential overdrafts when you’re juggling a million things, and this feature definitely helps mitigate that.
As for the credit building, I haven’t used it long enough to see significant changes in my score, but I love the idea of it. It’s like having a financial coach cheering you on.
The Overall Verdict
So, is Brigit: Cash Advance & Credit worth it? In my humble opinion, absolutely. It’s not just about getting a cash advance; it’s an all-around financial tool that helps you manage your money better. The app is perfect for anyone who occasionally finds themselves in a tight spot or wants a little help staying on top of their finances.
Sure, it’s not a magic wand that’ll solve all financial woes, but it’s definitely a handy tool to have in your financial toolkit. Remember, it’s always best to use it responsibly and not rely on it as a long-term solution. But for those moments when you need a little wiggle room or a nudge to keep your budget in check, Brigit has got your back.
Brigit: Cash Advance & Credit Pros and Cons
- Quick cash advances available instantly.
- User-friendly interface for easy navigation.
- No interest on cash advances, just fees.
- Helps monitor and improve credit score.
- Automated budgeting tools included.
- Monthly membership fee required.
- Limited to certain bank accounts only.
- Cash advance limits may be low.
- Requires access to bank account details.
- No option for joint accounts.
Brigit: Cash Advance & Credit Frequently Asked Questions
What is Brigit and how does it work?
Brigit is a financial app designed to help users manage their cash flow and improve their financial health. It offers features like cash advances, budgeting tools, and credit monitoring. Users can connect their bank accounts to the app, which analyzes their financial situation to offer personalized financial support and advice.
Is Brigit safe to use with my personal and financial information?
Yes, Brigit employs bank-level security with 256-bit encryption to protect your personal and financial data. The app does not sell your information to third parties, and it uses advanced security measures to ensure your data remains private and secure. Always ensure you download the app from official app stores to avoid security risks.
How much money can I borrow with Brigit's cash advance feature?
Brigit offers cash advances up to $250. The amount you qualify for depends on your financial situation and spending habits, which the app analyzes when you connect your bank account. The cash advance is designed to help users cover small, unexpected expenses without the need for traditional payday loans.
Does Brigit charge any fees for using its services?
Brigit offers a free version with limited features and a Plus subscription for $9.99 per month. The Plus version provides access to cash advances, credit monitoring, and other premium features. There are no interest charges on cash advances, making it a cost-effective option compared to traditional loans.
Can Brigit help improve my credit score?
Yes, Brigit includes tools for credit monitoring and education. While it doesn't directly improve your credit score, it provides insights and tips to help you manage your credit responsibly. By using Brigit's budgeting tools and avoiding overdrafts with cash advances, you can work towards a healthier credit profile.
Gallery